Major Global Banks Issue Urgent Warning Over AI Agentic Commerce Risks and Fraud Vulnerabilities

The financial sector is increasingly shifting its focus away from speculative science-fiction scenarios regarding artificial intelligence and toward immediate, tangible threats within the digital economy. While tech enthusiasts and AI researchers continue to debate existential risks involving artificial intelligence, a coalition of major international banking institutions has formally sounded the alarm over a much more grounded and imminent danger: widespread financial fraud, data privacy violations, and security vulnerabilities driven by autonomous shopping assistants.
On Tuesday, a powerful consortium of prominent global banks released a comprehensive joint position paper outlining deep-seated apprehensions regarding the rapid rise of AI agents designed to conduct commerce on behalf of consumers. The document, titled Building Trust in Agentic Commerce, serves as both a warning to the technology sector and a call to action. It outlines a strict framework of core principles that banks believe AI developers, platforms, and merchants must adopt to prevent catastrophic failures in consumer protection and payment security.
The consortium behind the initiative includes some of the largest financial services organizations in the world: Bank of America, Capital One, ASB Bank, Commonwealth Bank of Australia, ING Group, and NatWest Group. By uniting across international borders, these institutions hope to establish guardrails before autonomous AI shopping bots become deeply embedded in global consumer habits.
The Mechanics and Perils of Agentic Commerce
Agentic commerce represents a significant paradigm shift in how consumers interact with the digital marketplace. Unlike traditional e-commerce, where human users manually browse websites, compare prices, input payment credentials, and authorize transactions, agentic commerce delegates these tasks to autonomous or semi-autonomous AI assistants. These intelligent agents are designed to understand complex consumer prompts—such as finding the best deal on a flight, purchasing weekly groceries, or sourcing specific retail goods—and execute the entire purchasing cycle independently.
However, major financial institutions argue that the current technological trajectory is moving far faster than the security infrastructure required to support it safely. According to the banks’ joint principles paper, this new frontier introduces unprecedented safety risks, creating fertile ground for elevated rates of scams, financial fraud, and transaction disputes.
One of the primary concerns highlighted by the banking coalition involves mismatched expectations between consumers, AI agents, and merchants. For instance, disputes may frequently arise regarding the precise nature of a purchased product or service, the exact timing and execution of a transaction, and, most critically, legal liability. If an AI agent exceeds its authorized budget, purchases an incorrect item due to a hallucination or misinterpretation, or falls victim to a sophisticated cyberattack, it remains entirely unclear who bears the financial loss.
Furthermore, the paper warns that some technology providers and third-party developers may engage in dangerously unsafe practices. These include requiring consumers to hand over sensitive credit card details to be entered directly into unverified web forms, prioritizing payment methods that offer inferior consumer protections, and failing to comply with established payment processing standards and industry scheme rules.
A New Frontier for Cybercriminals and Social Engineering
Beyond accidental overspending or poor purchasing decisions, the banking consortium highlights the severe threat of malicious actors weaponizing AI shopping assistants. As automated commerce scales, cybercriminals are expected to develop novel attack vectors specifically designed to exploit autonomous agents.
These threats extend far beyond traditional phishing scams. Malicious entities could compromise, hijack, or impersonate AI agents, manipulating them into transferring funds to fraudulent accounts or purchasing counterfeit goods. Similarly, scammers could deploy rogue AI merchants capable of tricking consumer shopping bots into parting with funds under false pretenses. The paper notes that threat actors will likely pioneer sophisticated forms of social engineering tailored specifically to deceive algorithms rather than human users, bypassing traditional psychological red flags that consumers are typically trained to spot.
For merchants and small business owners, the proliferation of AI shopping bots threatens to trigger an administrative and financial nightmare. A sudden surge in automated purchasing errors is expected to cause a corresponding spike in credit card chargebacks, transaction disputes, and customer service burdens, straining the resources of legitimate online retailers.
Five Core Principles for a Safer AI Future
To mitigate these escalating risks, the banking consortium’s policy paper outlines five foundational principles that the artificial intelligence industry must embrace: Transparency, Safety, Privacy and Data, Choice, and Interoperability.
-
Transparency: AI developers and platforms must provide clear, understandable disclosures regarding how AI agents operate, how decisions are made, and what limitations exist. Consumers must always know when they are interacting with an autonomous agent and how transactions are being executed.
-
Safety: Safety protocols must be woven into the fabric of AI architectures from inception. This includes robust fraud detection, stringent authentication mechanisms, and clear liability frameworks that protect consumers and financial institutions when transactions go awry.
-
Privacy and Data: Financial institutions emphasize that AI companies must prioritize consumer consent and data privacy. Personal financial data, transaction histories, and credential details must not be harvested, improperly stored, or exposed to third-party vulnerabilities.
-
Choice: The financial sector believes that AI agents should foster a competitive, open marketplace rather than locking consumers into closed ecosystems or proprietary payment rails. Users must retain ultimate control over their preferred merchants and payment methods.
-
Interoperability: Autonomous shopping tools must be designed to work seamlessly across diverse banking networks, payment gateways, and retail platforms without compromising security standards or fragmenting the consumer experience.
The Timing: Vulnerabilities and Immediate Industry Backlash
The release of the Building Trust in Agentic Commerce paper occurred against a backdrop of intense technological upheaval, underscoring the immediate urgency of the banks’ warnings. The document was published within a 24-hour window of two major developments that dramatically highlighted the security vulnerabilities inherent in consumer-facing AI assistants.
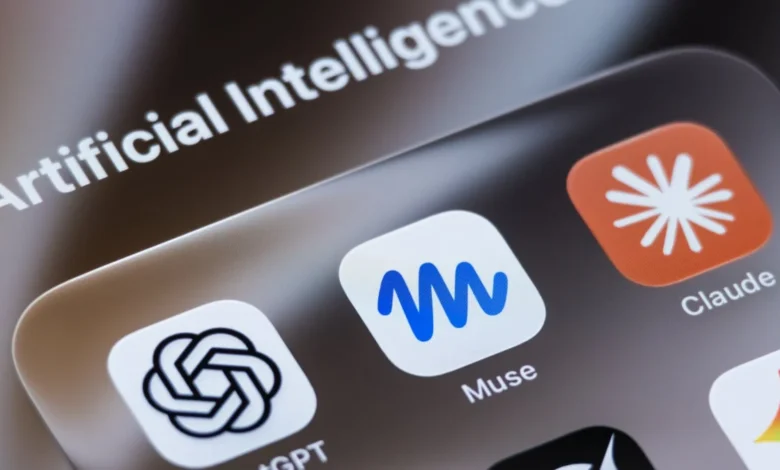
First came the widely reported discovery of a severe zero-day vulnerability within Meta’s Muse agentic AI assistant. The flaw exposed potential weaknesses in how autonomous agents handle external commands and secure data environments, raising alarms across cybersecurity communities.
Almost simultaneously, retail titan Amazon announced a decisive defensive maneuver: the e-commerce giant would actively block Meta’s Muse from making purchases or operating on its platform. Amazon’s swift action demonstrated that major merchants are already taking matters into their own hands to restrict autonomous agents that do not meet rigorous safety, privacy, and platform compliance standards.
These concurrent events validate the core anxieties expressed by Bank of America, Capital One, and their international peers. The rapid commercialization of agentic AI is outpacing the defensive capabilities of both retailers and financial institutions.
Broader Economic Implications and Path Forward
The intervention by global financial institutions signals a critical turning point in the governance of artificial intelligence. For years, regulatory discussions surrounding AI have focused primarily on copyright law, data scraping, algorithmic bias, and theoretical existential risks. The banking consortium’s initiative forcibly shifts the policy debate toward practical microeconomic stability and consumer financial protection.
As autonomous agents transition from experimental tech demos into mainstream tools capable of moving billions of dollars, the lack of standardized regulation and security frameworks poses a systemic risk to the global financial system. If consumers lose faith in the security of AI-driven commerce due to rampant fraud or unrecoverable losses, the adoption of agentic technologies could stall indefinitely.
Conversely, if technology companies, banks, and merchants can successfully collaborate around the five principles outlined in the new paper, agentic commerce could mature into a secure, efficient, and transformative pillar of the digital economy. For now, however, the financial sector has drawn a clear line in the sand: convenience cannot come at the expense of security, and the future of commerce must be built on trust rather than blind automation.