Tech Stocks Plunge as Midterm Election Results Signal a Pivot Away from AI Data Center Expansion

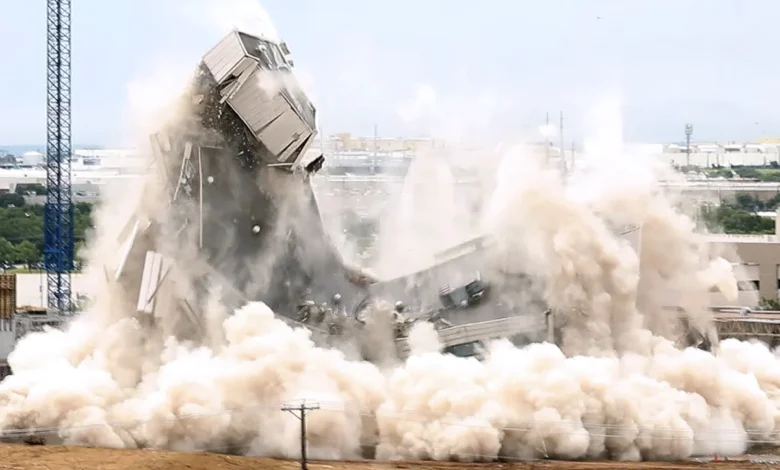
The euphoria that briefly gripped Wall Street following the U.S. midterm elections evaporated with startling velocity on Thursday, as a massive selloff in the technology sector wiped more than $3 trillion in market capitalization from the Nasdaq. While Tuesday’s election results, which saw Democrats regain control of both the Senate and the House of Representatives, were initially greeted with a relief rally, the fine print of the voter mandate—specifically regarding restrictive local and national ballot measures targeting AI infrastructure—has triggered a profound reassessment of the industry’s trajectory.
The Nasdaq Composite index plummeted by over 1,340 points, or 5.2%, during midday trading, marking its most severe daily retreat since the "Liberation Day" tariff announcements of April 2025. The carnage was widespread, affecting everything from semiconductor giants to gig economy platforms, but the epicenter of the volatility was firmly located in the hardware and infrastructure sector. The Philadelphia Semiconductor Sector index, a bellwether for the 30 largest chip-related firms, suffered a decline of over 1,000 points, putting it on track for its worst performance since the March 2020 market crash.
A Rapid Shift in Investor Sentiment
The reversal from Wednesday to Thursday represents a classic "buy the rumor, sell the news" scenario, compounded by a fundamental change in the regulatory landscape. Wednesday’s rally was driven by a belief that political gridlock had been broken, providing a clearer path for fiscal policy. However, as analysts and institutional investors parsed the specific outcomes of ballot initiatives—many of which explicitly target the environmental, energy, and land-use requirements of massive AI data centers—the long-term growth thesis for "Big Tech" began to look precarious.
The shift in sentiment is not merely speculative; it is grounded in a growing awareness that the physical limitations of the AI boom are meeting head-on with political resistance. For the past two years, the U.S. economy has been bolstered by a historic capital expenditure (capex) spree from the "Hyperscalers"—Alphabet, Microsoft, Amazon, Meta, and Oracle—alongside a surge of neocloud firms. This spending, totaling hundreds of billions of dollars, has fueled construction, energy procurement, and the mass acquisition of specialized networking gear and semiconductors. Thursday’s market action suggests that the era of unbridled expansion is facing a hard regulatory ceiling.
The Geography of the Data Center Standoff
At the heart of the investor panic is the realization that the geographic roadmap for AI expansion is being redrawn. States that were previously considered "friendly" to the massive energy demands of data centers, particularly Texas, are seeing a rise in local opposition to the environmental impact of these facilities.
Dan Ives, a prominent analyst at Yorkville Ives, highlighted the gravity of this shift in a note to clients. "While Big Tech and hyperscaler capex should still easily exceed $1 trillion in 2027, the growth rate into 2028 will clearly moderate significantly as the data center buildout comes at a much slower pace given the political map," Ives noted. His firm estimates that at least 10% of the planned 800 to 1,000 AI-focused data centers in the United States will now be removed from the development pipeline. Furthermore, up to 20% of remaining projects face an elongated regulatory approval process that could effectively stall capacity growth for years.
Industry Leaders Acknowledge New Realities
The industry is beginning to voice concerns that the "America-first" model of AI infrastructure might be becoming unsustainable. Dina Powell McCormick, President of Meta, provided a sobering perspective during a Wall Street Journal conference on Wednesday. She noted that the difficulty of building out domestic data centers is increasing, and confirmed that major hyperscalers are actively evaluating international alternatives.
"I can also tell you that every hyperscaler is now thinking about: ‘Do we need to build outside the United States?’ Because they’re enormous investments, hedging those investments is a wise thing to do," McCormick stated. This sentiment underscores a broader trend: as regulatory hurdles rise within the U.S., the competitive advantage of the American tech sector could be diluted by the necessity of moving high-capacity, energy-intensive AI operations to jurisdictions with more favorable permitting and energy regulations.
Winners and Losers in the Sector Selloff
The market reaction was particularly brutal for those companies most tethered to the infrastructure cycle. Semiconductor manufacturers, which have been the primary beneficiaries of the data center arms race, bore the brunt of the selling pressure. Micron Technology and Advanced Micro Devices (AMD) both saw their share prices crater by approximately 14% on Thursday. Nvidia, the poster child of the AI revolution, was down 8%, reflecting a broad loss of confidence in the short-term demand outlook for its high-end GPUs.
Neocloud companies—firms that have relied on significant debt financing to compete with the established giants—are in a particularly precarious position. Coreweave, a leading player in this space, saw its shares fall 9% on Thursday, marking an 18% decline over the preceding 48 hours. These companies are uniquely vulnerable because their business models require consistent, rapid deployment of new data center capacity to generate the revenue necessary to service their debt loads.
Conversely, the impact was more muted for companies with diversified revenue streams. Google, while still a major cloud provider, saw a relatively modest decline of 1.6%. The market appears to be distinguishing between companies that rely solely on the infrastructure buildout and those that possess established, high-margin advertising and software ecosystems that are less sensitive to the immediate pace of hardware installation.
Broader Economic Implications
The slowing of the AI infrastructure boom carries significant implications for the broader U.S. economy. Since 2023, the surge in capex has been a primary driver of non-residential construction spending and industrial production. If the data center buildout moderates, the ripple effects will be felt throughout the supply chain, from the raw material suppliers for cooling systems to the commercial real estate firms specializing in power-dense properties.
Furthermore, the uncertainty regarding AI infrastructure investment could lead to a tightening of credit markets for tech-focused infrastructure projects. As investors demand higher risk premiums, the cost of capital for firms like Coreweave or emerging neocloud entrants may rise, potentially forcing a consolidation within the sector.
Looking Toward 2028: A New Normal
The transition from a "growth at all costs" mentality to a "regulatory compliance and geographic hedging" strategy is now the dominant narrative in tech boardrooms. The political map, particularly following the midterm results, has sent a clear message: the physical infrastructure of the digital age is no longer a matter of private business prerogative but a subject of intense public and local scrutiny.
For investors, the immediate challenge is determining how much of this correction is a reflection of short-term political volatility versus a structural revaluation of the AI sector. The peak of capex growth, once projected to extend well into 2029, is now being pulled forward to 2026. This adjustment implies that while AI remains a transformative technology, the speed of its physical deployment will be subject to the friction of democratic governance, land-use disputes, and the global search for energy efficiency.
As the market closes the week, the focus will shift to how these companies recalibrate their fiscal guidance. Investors will be looking for signs of resilience in software and services that do not require massive, localized physical footprints. Meanwhile, the tech sector enters a period of introspection, grappling with the realization that the "Blue Tsunami" of political change has effectively washed away the certainty of an uninterrupted AI data center supercycle. Whether this represents a temporary pause or a more permanent moderation in the industry’s ambitions remains the defining question for the remainder of the decade.