Navigating the 2026 U.S. Housing Market: High Rates, Economic Uncertainty, and What Buyers Need to Know

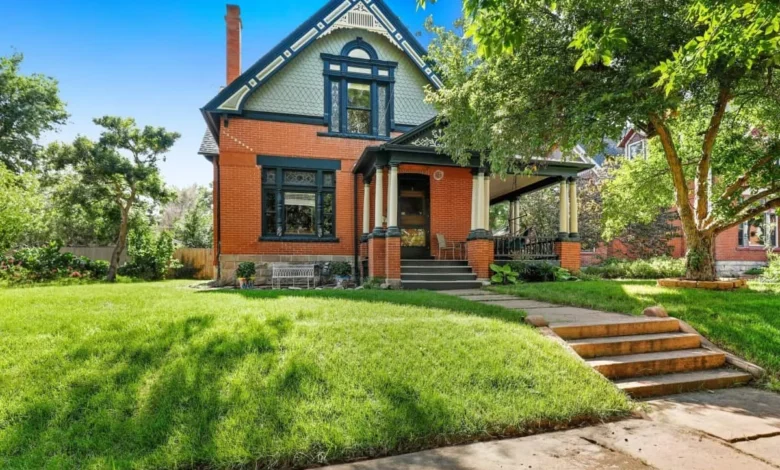
As the autumn season approaches, the traditional peak of the American housing market is drawing to a quiet close. However, for the vast majority of the country, a true peak never materialized. Following a historically sluggish 2025, the U.S. real estate sector continues to grapple with stagnant trends well into 2026, characterized by low sales volumes, restrained inventory levels, and near-record monthly carrying costs for prospective homeowners.
The persistent slowdown is no longer just a localized correction; it is the manifestation of a complex web of macroeconomic pressures. Chief among these challenges is a sharp spike in mortgage rates, which have climbed to 18-month highs. Prolonged geopolitical conflicts in the Middle East have reverberated through global energy markets, driving up crude oil prices, stoking renewed inflation fears, and sending shockwaves through the bond yield market.
Compounding these energy-driven pressures are broader global economic anxieties. Ongoing volatility tracked by the International Monetary Fund, shifting international trade policies and tariff uncertainties, heightened public anxiety regarding the socioeconomic role of artificial intelligence, and a surprisingly resilient domestic job market have kept financial institutions and consumers on edge. Because the labor market has consistently outperformed expectations despite tighter monetary policies, central bank watchers widely anticipate additional Federal Reserve rate adjustments, keeping borrowing costs elevated.
For millions of Americans weighing their financial futures, the central dilemma remains urgent: Should they dive into the 2026 housing market, or should they wait on the sidelines for more favorable economic conditions?
Expert Insights and Market Realities
According to Daryl Fairweather, Chief Economist at Redfin, the calculus of buying a home ultimately depends on individual financial readiness rather than trying to time a volatile macro environment.
"Now is a good time to buy a home, if you can afford it," Fairweather notes. "Prices keep climbing, which is pushing some buyers out of the market but giving those who remain an upper hand in negotiations. The conflict in the Middle East, ballooning mortgage rates, and a volatile economy are making everyone wary, though, and local housing markets vary widely. Buyers serious about making offers should consult a local agent, understand their market dynamics, and be confident in their finances and future income."
To evaluate whether entering the market is prudent, prospective buyers must analyze the structural pillars defining the current real estate landscape: home valuations, mortgage financing trends, inventory shifts, and regional demand disparities.
House Prices Remain High, Though Growth is Moderating
The national median sale price for a home in the United States currently stands at $398,596, representing a modest 2.2% increase compared to the same period last year. More broadly, home valuations remain nearly 20% higher than they were five years ago, locking many middle-class buyers out of traditional entry points.
This severe affordability squeeze has created a protracted standoff between buyers and sellers. Many potential participants have opted to stay on the sidelines, waiting for price corrections or lower financing costs. This hesitation has allowed inventory to accumulate slowly, creating a unique tug-of-war dynamic. While overall price growth has decelerated significantly from the blistering 7% annual surges seen between 2012 and early 2020, prices continue to edge upward, heavily favoring affluent buyers and ultra-wealthy investors who can bypass high mortgage rates entirely with all-cash offers.

Longer-term projections suggest that market affordability will gradually improve as wage growth eventually outpaces home price increases and general inflation cools. Nevertheless, the immediate reality for everyday buyers remains challenging.
Mortgage Rates Hover Near Multi-Year Highs
Financing a home has become markedly more expensive. As of mid-September, the weekly average interest rate for a standard 30-year fixed mortgage sits at 7.17%, touching levels not seen since January 2025. Prior to March of this year, rates had stabilized in a slightly more manageable band between 6.1% and 6.3%.
Chen Zhao, Head of Economics Research at Redfin, points directly to international instability as the primary catalyst for the surge. "Mortgage rates have continued to climb since March almost entirely because of the conflict in the Middle East and its effects on global energy prices, inflation, and bond yields," Zhao explains. "As oil prices have shot up and inflation fears have grown, interest rates have risen in tandem. Time will tell how the conflict will ultimately impact the U.S. economy and housing market, but so far it has put significant upward pressure on inflation and mortgage rates."
Because mortgage rates dictate the fundamental math of monthly housing budgets, these increases have profound consequences. Even minor fluctuations in the interest rate can alter a homebuyer’s lifetime financing costs by tens of thousands of dollars, directly impacting debt-to-income ratios and qualification limits.
Shifting Power Dynamics: A Regional Tale of Buyers and Sellers
Despite high borrowing costs, the broader market dynamics have subtly tipped in favor of active buyers—at least in specific geographic pockets.
Total active housing inventory has climbed above 1.5 million units nationwide. While this figure remains historically low compared to pre-pandemic baselines, it represents the highest monthly inventory level recorded since 2020. This supply accumulation has given serious buyers unprecedented leverage to demand seller concessions, such as financing for rate buy-downs or funds for home repairs.
However, the housing market is far from uniform. Regional divergences are stark:
- The Sun Belt Surplus: Metros across the Sun Belt—most notably Austin, Texas, which has transitioned into one of the slowest-moving major housing markets in the nation—have experienced a surge in housing inventory driven by aggressive new construction. Buyers here hold significant negotiating power.
- The Northeast and Midwest Resurgence: Conversely, supply remains severely restricted in competitive pockets of the Midwest and the Northeast. Affordable markets surrounding New York, such as Rochester and Buffalo, continue to experience high demand, driving up prices and firmly entrenching a seller’s market. The San Francisco Bay Area has also witnessed a localized resurgence in buyer competition.
Navigating Economic Uncertainty: Strategic Guidance for Buyers
For consumers attempting to purchase real estate amid intersecting economic pressures, including potential tariff impacts and monetary policy shifts, real estate analysts recommend a disciplined, step-by-step approach.
- Conduct a Thorough Financial Audit: Assess savings, existing debt-to-income ratios, and credit profiles. Establishing a robust emergency fund—ideally covering three to six months of living expenses—is vital to absorb unexpected maintenance costs and market fluctuations.
- Evaluate True Monthly Carrying Costs: Beyond the base mortgage payment, buyers must accurately budget for escalating property taxes, mandatory homeowners insurance, and ongoing home maintenance. With climate risks prompting insurers to non-renew policies in disaster-prone regions, insurance costs require rigorous upfront vetting.
- Prioritize Personal Stability: Real estate is fundamentally a long-term commitment. Buyers should ensure their employment income and geographic roots are secure before locking themselves into a multi-year financial obligation.
- Partner with Local Expertise: Because macroeconomic trends manifest differently down to the neighborhood level, retaining an experienced local real estate agent and securing mortgage pre-approval are essential prerequisites for moving decisively when a suitable property emerges.
Ultimately, market experts emphasize that the ideal time to purchase a home is dictated less by unpredictable macroeconomic forecasts and more by personal financial readiness. While waiting for mortgage rates to retreat remains tempting, prolonged hesitation risks exposing buyers to heightened competition and future price escalation if broader economic conditions eventually stabilize.