Tech Stocks Stage Cautious Recovery Following Historic Post-Midterm Rout Driven by AI Policy Concerns

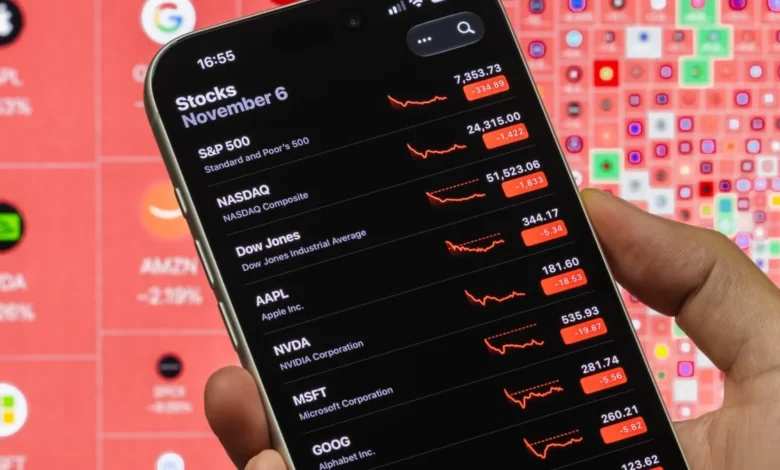
The technology sector attempted to steady itself on Friday following one of the most volatile trading sessions in recent memory, as opportunistic investors stepped in to buy the dip after a historic market sell-off. The sudden and severe downturn earlier in the week was triggered by the unexpected outcomes of the U.S. midterm elections, which sent shockwaves through Wall Street and cast a shadow of regulatory uncertainty over the artificial intelligence and broader technology industries.
While Friday’s recovery offered a welcome reprieve for market participants, major indexes and bellwether stocks remained well below their pre-election levels, underscoring deep-seated anxieties regarding the shifting political landscape in Washington and its potential implications for corporate innovation, data infrastructure, and regulatory oversight.
The Anatomy of the Rout: Midterm Results and Political Shift
The turbulence began immediately following the U.S. midterm elections, where Democratic candidates secured resounding victories across several key congressional and gubernatorial races. The political shift fundamentally altered the perceived regulatory environment for the technology sector, which has enjoyed a largely accommodating backdrop in recent years.
During the election cycle, a significant faction of prominent tech industry leaders—including high-profile figures such as SpaceX and Tesla CEO Elon Musk—publicly aligned themselves with President Donald Trump and the Republican Party. This overt political positioning, combined with heavy financial backing from Silicon Valley elites, has left the industry vulnerable to potential political blowback now that Democrats have strengthened their legislative footprint.
Market analysts noted that many victorious Democratic candidates ran campaigns explicitly critical of the rapid, largely unchecked expansion of artificial intelligence. Critics pointed to environmental concerns regarding the massive energy and water consumption of data centers, as well as labor displacement and privacy risks associated with advanced machine learning models.
The political fallout was swift. Just one day after the midterm election results were finalized, Senator Bernie Sanders escalated legislative concerns by formally calling for a national moratorium on the construction of new data centers. The proposal, aimed at curbing the unchecked environmental footprint of energy-intensive AI training facilities, served as a primary catalyst for the steep market sell-off that followed.
Market Chronology: From Record Highs to Panic Selling
The sequence of events unfolded rapidly over a brutal 48-hour trading window that caught institutional and retail investors largely off guard.
On Monday, ahead of the election results, tech equities were trading near stable levels, buoyed by strong third-quarter earnings reports and robust demand for enterprise AI solutions. However, early exit polls and incoming election returns on Tuesday began to signal a strong performance by the Democratic opposition, introducing immediate policy risk into valuation models.
By Wednesday, the full realization of the midterm outcomes hit the trading floor. Senator Sanders’ announcement regarding a proposed data center moratorium galvanized fears of impending federal intervention. Wall Street reacted with immediate risk-off behavior, shedding positions across high-multiple growth stocks, semiconductor manufacturers, and cloud computing infrastructure providers.
The panic culminated on Thursday in what financial historians are already categorizing as one of the worst single-day routs for the sector in six years. The tech-centric Nasdaq 100 plummeted 6.3 percent in a broad-based liquidation event. High-flying artificial intelligence darlings, mega-cap platform companies, and semiconductor pioneers alike faced relentless selling pressure as algorithmic trading desks and risk managers slashed exposure to the sector.
Friday’s Partial Rebound: Buying the Dip
By Friday morning, the mood on the trading floor shifted from panic to calculated opportunism. Recognizing that the fundamental demand drivers for artificial intelligence and digital services remain intact despite the regulatory headwinds, institutional buyers began stepping in to scoop up undervalued assets.
The Nasdaq 100 managed a 1.9 percent recovery by the end of the session. While modest compared to Thursday’s staggering losses, the upward movement provided a psychological floor for a market shaken by sudden political risk.
Individual equities mirrored this tentative recovery. Nvidia, a primary barometer for the artificial intelligence hardware market, saw its share price rise by 7 percent during Friday’s session. Similarly, aerospace and defense-tech pioneer SpaceX experienced a 6.1 percent bump in private market evaluations and secondary indicators. Despite these daily gains, neither company had fully recouped the ground lost during Thursday’s historic correction.
Other segments of the technology ecosystem experienced even stronger relief rallies as investors hunted for bargains. Intel, striving to reclaim its footing in the domestic semiconductor manufacturing race, surged 8.9 percent. Meanwhile, consumer tech platform Airbnb jumped 11.7 percent, benefiting from a rotation back into consumer-facing digital services.
Chipmakers and infrastructure providers—sectors most directly exposed to potential regulatory bottlenecks and environmental restrictions—lagged slightly behind the broader recovery but nonetheless finished the day in positive territory. Analysts noted that while the immediate sell-off may have overshot rational valuation adjustments, the underlying fear regarding future policy constraints remains a permanent fixture of market sentiment for the foreseeable future.
Industry Reactions and Corporate Posture
As corporate boardrooms in Silicon Valley digest the new political reality, reactions from industry associations and corporate leadership have focused on emphasizing the economic contributions of the technology sector.
While public statements from major tech executives have remained measured, industry lobbyists have already mobilized to engage with lawmakers on both sides of the aisle. Representatives for major cloud providers and semiconductor firms argue that sweeping measures like a national data center moratorium would inadvertently cede American leadership in artificial intelligence to global competitors, notably China.
Proponents of the technology sector emphasize that modern data centers are increasingly turning to renewable energy sources and investing in advanced cooling technologies to minimize their ecological footprint. They contend that punitive legislative frameworks risk crippling domestic innovation rather than guiding it toward sustainable practices.
Conversely, environmental groups and consumer advocacy organizations have praised lawmakers for addressing the unchecked growth of AI infrastructure. These groups argue that the massive strain placed on municipal electrical grids by generative AI workloads necessitates federal oversight and localized planning to protect utility consumers from soaring electricity bills and grid instability.
Fact-Based Analysis of Broader Implications
The events of the past week highlight a fundamental structural shift in how financial markets price regulatory and political risk within the technology sector. For over a decade, major tech equities benefited from a relatively permissive regulatory environment characterized by minimal federal intervention and robust bipartisan support for digital innovation.
The post-midterm market reaction demonstrates that this era of frictionless growth may be drawing to a close. Key implications of this evolving dynamic include:
- Valuation Re-pricing: Investors are beginning to incorporate a "regulatory discount" into the valuation models of artificial intelligence and cloud computing firms. The assumption that technological innovation will proceed entirely unfettered by government oversight is being replaced by a more cautious outlook.
- Infrastructure Bottlenecks: Proposals such as data center moratoria, if translated into actual legislative or executive action, could fundamentally alter the deployment timeline for next-generation AI models. Companies relying on rapid scaling of compute power may face increased capital expenditures, prolonged permitting processes, and geographical relocation constraints.
- Political Risk Management: The overt political alignments of certain tech leaders during the 2024 election cycle have introduced idiosyncratic risk to specific companies. Corporate governance experts suggest that major technology firms may need to adopt a more politically neutral posture to insulate themselves from partisan legislative retaliation.
- Resilience of Core Demand: Despite short-term volatility, Friday’s market recovery underscores the fundamental strength of enterprise demand for digital transformation. While regulatory hurdles may slow the pace of deployment, the overarching economic imperative for automation, cloud migration, and artificial intelligence integration remains robust.
As Wall Street looks ahead to the upcoming legislative sessions in Washington, market participants will be closely monitoring congressional committee appointments, proposed energy regulations, and any formal legislative drafts stemming from the Democratic midterm victories. For now, the tech sector has narrowly averted a prolonged freefall, but the path forward will require navigating a significantly more complex and contentious political landscape.