The Complete Guide to Buying a Mobile Home: Costs, Financing, and Essential Considerations for First-Time Buyers

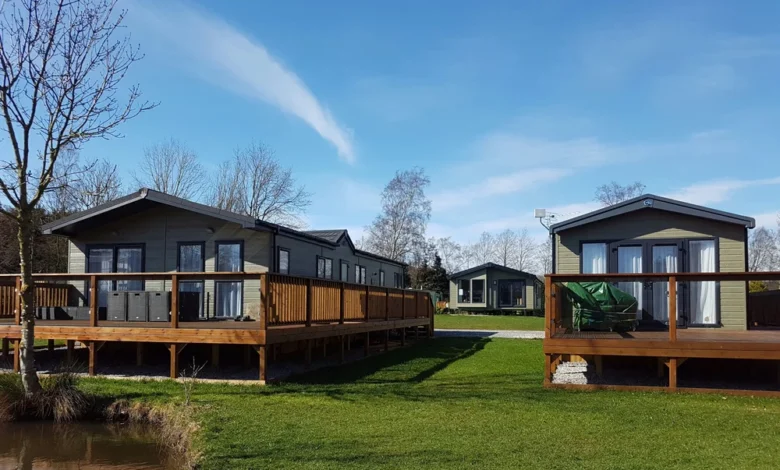
Mobile homes have rapidly emerged as a viable pathway to homeownership for first-time buyers navigating an increasingly expensive housing market. Driven by regulatory shifts like the provisions within the ROAD to Housing Act—which streamline the construction, placement, and accessibility of factory-built housing—manufactured homes are gaining renewed attention from consumers and policymakers alike. However, acquiring a mobile home involves a complex web of financial, logistical, and legal considerations that extend far beyond simply purchasing the physical structure. Prospective buyers must carefully weigh variables such as financing mechanisms, land ownership, local zoning laws, professional installation, and ongoing maintenance to make an informed investment.
Evolution and Industry Background
To fully understand the current market dynamics of mobile homes, it is necessary to examine their historical evolution and regulatory framework. Historically, the term "mobile home" referred broadly to factory-built housing constructed prior to the implementation of federal safety and construction standards. In contrast, modern manufactured homes are strictly regulated by the U.S. Department of Housing and Urban Development (HUD), which established the Federal Manufactured Home Construction and Safety Standards in June 1976.
Recent legislative developments have further transformed the industry. The passage of the ROAD to Housing Act introduced critical updates, including provisions that remove previous requirements for a permanent metal chassis on certain homes. While eliminating the chassis removes the physical ability to relocate the home, it substantially reduces overall production costs and expands modern floor plan options, anchoring these properties more permanently to their sites. Consequently, contemporary industry data indicates that the vast majority of modern manufactured homes never actually move once they are initially placed.
Structural Types and Cost Breakdown
When entering the market, buyers generally encounter three primary configurations of manufactured housing, each varying significantly in layout, square footage, and pricing:
- Single-Wide Homes: Featuring a single, compact section, these units typically range from $40,000 to $100,000. They offer the most affordable entry point into homeownership but provide limited living space.
- Double-Wide Homes: Comprising two connected sections, double-wides offer expanded living areas and generally range from $95,000 to $150,000.
- Triple-Wide Homes (and larger): Built using three or more sections, these homes frequently exceed 2,000 square feet and command prices starting at $150,000 and above.
These illustrative price ranges fluctuate widely depending on regional market conditions, the age of the structure, and whether the purchase price includes delivery, professional setup, or the underlying land.
Hidden Costs and Site Preparation
Industry experts emphasize that the sticker price of a mobile home represents only part of the total financial commitment. Buyers frequently overlook preparatory and post-closing expenses that are essential for safe habitation and regulatory compliance.
According to regional specialists such as Desert Mobile Home Services in Arizona, unbudgeted expenses often include specialized labor for leveling, skirting, utility connections, and the installation of protective anchoring systems. "Tie-downs may be required by a lender, engineer, or as part of the financing process, so they should be addressed early rather than waiting until the last minute," the firm notes. These structural anchors secure the home against severe weather and ground shifting over time.
Additional preparatory costs often encompass boundary surveys, local permits, grading, and the installation of septic systems or well hookups if the home is placed on private property.
Land Ownership Versus Community Living
A foundational decision for any mobile home buyer is determining where the structure will reside. Options generally fall into two categories: placing the home in an established land-lease community or locating it on private property owned by the buyer.
Purchasing a home within a mobile home park or community typically involves owning the physical structure while renting the underlying plot of land. While this arrangement often grants access to shared amenities and maintained infrastructure, residents must factor ongoing monthly lot rent, community bylaws, and potential rent increases into their long-term budgets. Furthermore, financial analysts frequently point out that homes situated on leased land tend to depreciate more rapidly than traditional site-built real estate because the owner does not capture the appreciation of the underlying land.
Conversely, placing a manufactured home on private land grants greater property control and long-term equity potential. However, buyers must navigate local zoning ordinances, municipal permitting processes, and utility extension costs before placement can occur.
Financing Strategies and Specialized Loan Products
Securing adequate financing requires careful planning, as manufactured homes are subject to distinct lending criteria compared to traditional site-built properties. Cameron Jóvan, founder of the homebuilding platform PERCH, stresses the importance of sorting out financial arrangements early in the process: "Decide how you’ll finance the home before you fall for a floor plan, because that choice shapes everything else. Manufactured homes are built to the federal HUD code and can be financed as personal property or real property, depending on the home and the land."
Depending on how the home is classified legally and whether land is included in the purchase, several financing avenues exist:
- Chattel Loans: Commonly utilized when a mobile home is classified as personal property—frequently occurring when the home is placed on leased land—chattel loans function similarly to auto loans or personal property liens rather than traditional mortgages.
- Government-Backed Loans: Qualified buyers may access FHA, VA, or USDA loan programs, which offer government-insured financing options for eligible manufactured homes and real property arrangements, occasionally featuring zero-down-payment incentives.
- Conventional Mortgages: Traditional lenders may finance manufactured homes that are permanently affixed to a foundation and classified as real estate, subject to strict property age, condition, and title requirements.
- Personal Loans: Serving as a fallback option when traditional manufactured housing loans are unavailable, personal loans offer flexibility but typically carry higher interest rates and shorter repayment terms.
Expert Insights and Risk Mitigation
Navigating the acquisition process requires rigorous due diligence, particularly regarding contractual agreements and property condition. Industry veterans caution buyers to scrutinize every detail before executing a final purchase agreement.
Ivan Kosobucki, founder of PrefabFind, highlights the critical nature of contract review, especially when purchasing custom or new factory-built models. "One thing we often see buyers overlook is the contract: before signing, have an independent professional review it to ensure the terms are fair and clearly explain what happens if the manufacturer delays delivery, fails to meet its obligations, or goes bankrupt," Kosobucki advises.
Similarly, the team at Henley Homes in Sulphur Springs, Texas, warns buyers to remain vigilant against unclear fee structures, vague delivery responsibilities, and undocumented verbal promises from retailers. They recommend thoroughly researching the dealer’s financial stability and ensuring all warranty terms and setup obligations are explicitly detailed in writing.
Once a home is selected—whether new or pre-owned—securing a professional evaluation is vital. Jesse Weaver of Northwest Home Inspector in Washington State underscores the value of specialized expertise: "Hiring a seasoned home inspector who specializes in mobile homes to go over all of the intimate details of the property with you is worth its weight in gold. You will feel much more prepared when you make a decision with all of the knowledge you will gain." Inspectors evaluate crucial elements such as the HUD certification label, roof integrity, subflooring condition, plumbing, and the underbelly enclosure.
Implications and Broader Market Outlook
As housing affordability remains a central economic challenge, manufactured housing is expected to play an increasingly vital role in residential real estate markets, offering viable alternatives not only for first-time buyers but also for aging populations seeking accessible downsizing options. Representatives from Collective Communities note that manufactured housing provides an attractive alternative to traditional senior living facilities, emphasizing that buyers must evaluate neighborhood culture, management quality, and infrastructure alongside the physical dwelling.
Ultimately, while mobile homes offer a more accessible entry point to property ownership, their long-term viability depends on meticulous financial planning, comprehensive property inspections, clear understanding of land tenure, and strict adherence to local regulatory frameworks.