Rotana CEO Philip Barnes Urges Caution on Gulf Hotel Booking Data as Regional Geopolitical Tensions Alter Travel Patterns

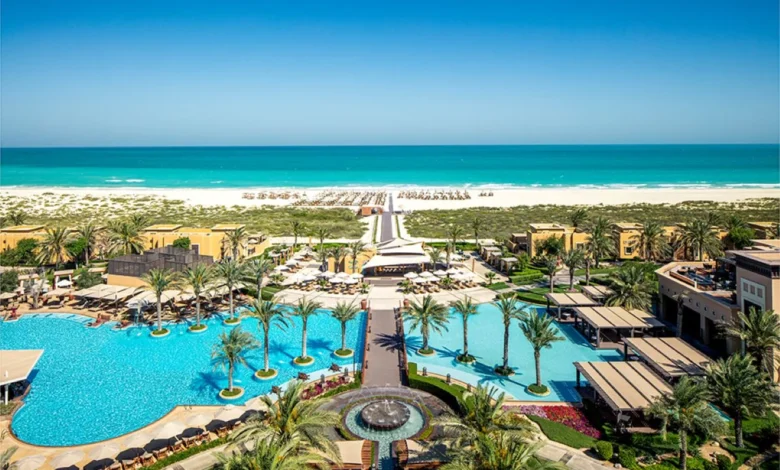
The hospitality sector in the Middle East is currently navigating a period of unprecedented operational complexity, defined by shifting consumer behavior, compressed booking horizons, and persistent geopolitical friction. Abu Dhabi-headquartered hotel management company Rotana has cautioned industry stakeholders and financial analysts against relying on traditional forward-looking reservation metrics to gauge fourth-quarter performance. The warning comes as ongoing volatility associated with the U.S.-Iran conflict continues to influence travel patterns across the Gulf Cooperation Council (GCC) region, causing traditional booking windows to contract dramatically.
According to leadership at Rotana, forward-looking data no longer serves as a reliable barometer for actual occupancy and revenue generation. While advance reservations for the final quarter of the year appear substantially depressed when measured against historical benchmarks, executive leadership emphasizes that this trend reflects a broader structural change in consumer booking habits rather than a permanent contraction in travel demand. As travelers adopt an increasingly cautious and spontaneous approach to trip planning, regional hoteliers are forced to adapt to a landscape where revenue materializes at the eleventh hour.
The Shrinking Booking Window Phenomenon
The phenomenon of the narrowing booking window has become the defining operational hurdle for hoteliers operating in the Middle East and surrounding feeder markets. Historically, leisure and corporate travelers to the Gulf secured accommodations weeks or months in advance, allowing property managers to forecast revenue streams with a high degree of accuracy. However, heightened regional security concerns, fluctuating flight availability, and evolving travel advisories have fundamentally altered this timeline.
Philip Barnes, Chief Executive Officer of Rotana, highlighted the disconnect between forward-looking indicators and realized performance by pointing to recent operational results. While forward data for the months of August and September similarly pointed toward sluggish occupancy levels, both months ultimately delivered robust operational results driven by last-minute demand.
To illustrate the extreme nature of current consumer behavior, Barnes cited a recent transaction at a Rotana property involving a group of 45 German tourists who secured their reservations with a mere two days’ notice. This compressed timeline has become increasingly common, requiring revenue management systems, front-desk personnel, and housekeeping departments to operate with maximum flexibility. Hoteliers can no longer depend on early-stage pipeline data to make staffing, inventory, and pricing decisions, forcing a pivot toward agile, short-cycle operational strategies.
Geopolitical Backdrop and Regional Sentiment
The underlying driver of this behavioral shift is the prolonged strategic friction between the United States and Iran, which casts a long shadow over the stability of the broader Middle East. While major tourism hubs in the United Arab Emirates, Qatar, and Oman remain secure and far removed from active hostilities, the psychological impact of geopolitical headlines on international travelers cannot be understated.
Travelers originating from long-haul markets often struggle to differentiate between localized geopolitical disputes and broader regional safety risks, leading to a pervasive wait-and-see attitude. This hesitation manifests primarily as delayed decision-making. Rather than canceling planned vacations or business trips outright, prospective visitors are waiting until the final possible moment to confirm travel arrangements, seeking reassurance that regional air corridors remain open and security conditions remain stable.
Industry analysts note that this pattern creates a uniquely challenging environment for property owners and asset managers. Fixed overhead costs, labor requirements, and maintenance schedules must be managed against a backdrop of revenue visibility that rarely extends beyond a week or two. Consequently, hotel operators are leaning heavily on dynamic pricing algorithms and targeted domestic marketing to cushion the impact of unpredictable international arrivals.
Shifting Source Markets and International Recovery
Despite the headwinds generated by geopolitical uncertainty, the Middle East hospitality sector continues to benefit from a gradual diversification of its international source markets. Traditional European markets, which historically formed the bedrock of winter tourism in the UAE, are showing signs of steady, albeit cautious, recovery.
Barnes noted that inbound travel from Germany and Russia is beginning to return, with both nations remaining core focus points for Rotana’s commercial and marketing teams. However, overall travel volumes from these European corridors have yet to return to pre-conflict levels. The hesitation among European travelers is largely attributed to cautious corporate travel policies and conservative risk assessments by major tour operators, many of which remain sensitive to regional news cycles.
At the same time, the void left by delayed European arrivals is being partially offset by resilient demand from emerging and established Asian markets. China and India have emerged as vital economic pillars for the Gulf tourism economy. Outbound travel from India continues to surge, driven by strong economic growth, improved air connectivity, and a preference for the UAE as a secure, luxury-oriented destination for weddings, corporate retreats, and family leisure travel. Similarly, the ongoing recovery of Chinese outbound tourism has provided a much-needed boost to luxury hotels and retail complexes across Abu Dhabi and Dubai.
Broader Economic and Industry Implications
The broader implications of compressed booking windows extend far beyond individual hotel balance sheets, influencing the entire regional tourism ecosystem. Airlines, destination management companies, event organizers, and retail operators are all adjusting their operational models to align with last-minute consumer habits.
For airlines operating in the region, the late-booking trend complicates capacity planning and yield management. Carriers are forced to maintain pricing flexibility closer to departure dates, which can impact profitability if demand spikes unexpectedly or leaves aircraft operating with vacant seats. Meanwhile, the meetings, incentives, conferences, and exhibitions (MICE) sector—historically a major contributor to mid-week hotel occupancy in the UAE—is experiencing longer deliberation cycles as corporate planners weigh risk management protocols before committing to large-scale gatherings.
From an investment perspective, financial institutions and real estate developers monitoring the hospitality sector are taking a pragmatic view of current performance metrics. Asset valuations and lending terms are increasingly factoring in the cyclical and event-driven nature of regional travel. Rather than penalizing hoteliers for weak forward-booking numbers, sophisticated investors are analyzing trailing performance and the agility of management teams in capturing last-minute demand.
Outlook and Strategic Adaptation
Looking ahead, industry leadership remains cautiously optimistic, adopting a balanced perspective that avoids both unwarranted pessimism and unfounded exuberance. As Barnes articulated, the current market reality is neither "doom and gloom nor gangbuster business" and will likely remain in this transitional state until the broader geopolitical environment achieves a durable settlement.
To thrive in this volatile climate, hospitality groups like Rotana are focusing on variables within their direct control. This includes enhancing direct-to-consumer digital booking channels to capture spontaneous demand, offering flexible cancellation policies to instill consumer confidence, and deepening engagement with high-yielding domestic and regional staycation markets. By maintaining operational agility and closely monitoring shifting source-market dynamics, the Gulf hospitality sector aims to weather the current period of uncertainty while positioning itself to capture pent-up demand the moment regional stability is firmly re-established.