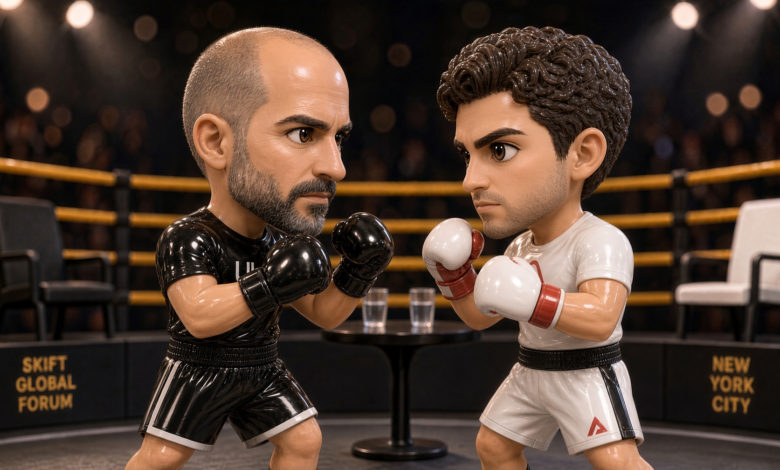
The global travel and transportation ecosystem is currently witnessing one of the most intriguing strategic convergences in corporate history, as two giants born outside the traditional hospitality sector make aggressive plays for the hotel booking market. Under the leadership of CEO Dara Khosrowshahi, ride-hailing and delivery titan Uber is intensifying its push into travel accommodations, leveraging its massive daily active user base and high-frequency engagement model. Simultaneously, home-sharing pioneer Airbnb—which famously disrupted the lodging industry by offering private apartments and homes—continues to eye the broader travel market to capture deeper intent from its consumer base. This high-stakes competitive dynamic raises a fundamental question about modern digital commerce: does daily user frequency, as demonstrated by Uber, travel further than explicit travel intent, the foundational advantage possessed by platforms like Airbnb?
To understand the weight of this impending rivalry, one must examine the philosophical roots of platform expansion. Historically, digital commerce has been governed by the principle of reducing friction and capturing a larger share of the consumer wallet. Traditional Online Travel Agencies (OTAs) such as Expedia, Booking Holdings, and Tripadvisor were built on the premise of travel intent. A consumer decides to take a trip, visits an OTA, and subsequently books flights, hotels, car rentals, and excursions. Under the guidance of Khosrowshahi, who served as Expedia’s CEO from 2005 to 2017, this model was refined and scaled globally. Khosrowshahi mastered the art of the multi-product online travel ecosystem, demonstrating that a flight booking could seamlessly cross-sell into a hotel reservation, which in turn could generate ancillary revenue through car rentals and destination packages.
When Khosrowshahi transitioned to Uber in 2017, he did not abandon this playbook; rather, he inverted it. Instead of starting with an occasional event—a vacation or a business trip—and building outward, Uber began with a daily or weekly necessity: urban mobility. By anchoring its platform to the frequent habit of hailing rides, Uber established a dominant consumer touchpoint. Over the subsequent years, this high-frequency infrastructure was systematically expanded. Rides naturally birthed Uber Eats, which evolved into grocery delivery, parcel shipping, and local commerce. Now, Uber is systematically completing the circle by integrating travel deeper into its application, moving beyond airport rides and transit partnerships to offer direct hotel bookings.
The convergence of these business models brings to light contrasting strategic advantages. Uber’s primary asset is frequency. Millions of consumers open the Uber application multiple times a week, if not multiple times a day. This creates a powerful behavioral loop, high top-of-mind awareness, and an entrenched payment infrastructure. When a user opens an app habitually for a commute or lunch delivery, the barrier to considering that same app for a weekend getaway or business trip is significantly lowered. The platform does not need to spend excessive capital acquiring the customer for that initial moment of consideration because the customer is already actively engaged with the interface.
Conversely, Airbnb occupies the opposite end of the strategic spectrum, commanding definitive travel intent. When a user opens Airbnb, there is rarely any ambiguity regarding their purpose: they are planning a trip, looking for accommodation, and evaluating destinations. This provides Airbnb with profound contextual relevance. While Airbnb started as an alternative to hotels—offering spare rooms, treehouses, and suburban homes—its long-term trajectory has steadily crept closer to traditional hospitality. To sustain its growth targets as its core alternative-accommodation market matures in certain urban and suburban centers, Airbnb must capture more segments of the broader travel pie, including traditional hotel inventory and enhanced experiential offerings.
The Chronology of Platform Convergence and Expansion
The roots of Uber’s modern travel ambitions trace back to its earliest attempts at diversification, but the acceleration of this strategy has been most visible over the last five years. Following the disruptions of the COVID-19 pandemic, travel demand rebounded with unprecedented velocity, prompting technology platforms to reassess how they could capture post-pandemic consumer spending.
In late 2021 and early 2022, Uber took decisive steps to integrate trains, flights, and buses into its application in the United Kingdom, partnering with local ticketing platforms as part of a broader vision to become a "Super App" for mobility. This initiative served as a testing ground for consumer appetite. If a commuter could book a train ticket alongside a rideshare, the logical next step was incorporating overnight accommodations. Throughout 2023 and 2024, Uber expanded its travel features, utilizing white-label technological partnerships and strategic integrations to allow users to book hotels directly through the platform in select markets.
Parallel to Uber’s evolution, Airbnb has undergone its own chronological transformation. Founded in 2008 during the global financial crisis, Airbnb spent its first decade proving that everyday people would rent out their spare spaces to strangers. By the late 2010s, however, the company recognized that professional property managers and boutique hotels represented a massive, untapped segment of supply. Airbnb launched initiatives like Airbnb Plus and integrated boutique hotels onto its platform, blurring the lines between alternative lodging and traditional hospitality.
During the pandemic, Airbnb demonstrated remarkable agility, shifting its supply from dense urban centers to rural and suburban markets where travelers sought isolation and domestic getaways. As international travel returned, Airbnb focused heavily on refining its core application, introducing sweeping product upgrades twice a year to improve search functionality, guest reliability, and host tools. However, the underlying strategic challenge remained: how to leverage its unmatched travel intent to keep users within its ecosystem when they are not actively booking a vacation home.
Market Dynamics and Financial Implications
Analyzing the financial and market implications of this duel requires looking at the economics of customer acquisition cost (CAC) and lifetime value (LTV). For traditional OTAs, acquiring a travel customer is becoming increasingly expensive due to rising digital advertising costs on search engines and social media platforms. OTAs must spend heavily to capture search intent at the exact moment a consumer decides to travel.
Uber bypasses a significant portion of this traditional customer acquisition funnel. Because its users are already inside the application for daily utility, the marginal cost of presenting a hotel offer is remarkably low. Furthermore, Uber’s rich trove of first-party data—spanning commuting patterns, dining habits, and frequent airport trips—allows the company to deploy highly targeted, context-aware marketing. If an Uber user frequently takes rides to a specific financial district in another city, or routinely requests rides to airports on Sunday evenings, the platform can surface targeted hotel promotions long before the user actively begins searching on an OTA.
On the other hand, Airbnb’s monetization model is deeply tied to the higher average order value (AOV) of travel. While a typical Uber ride or meal delivery yields a modest transaction value with high frequency, a travel booking on Airbnb often spans multiple nights and hundreds or thousands of dollars, yielding a substantial commission per transaction. Airbnb’s advantage lies in the depth of engagement during the planning phase. When users plan a trip on Airbnb, they spend considerable time browsing, saving listings to wishlists, and researching neighborhoods. This deep engagement gives Airbnb an intimate understanding of consumer travel preferences, which can theoretically be leveraged to cross-sell complementary services, such as local experiences, car rentals, and potentially traditional hotel rooms.
Industry Reactions and Strategic Responses
The aggressive expansion of tech platforms into the hotel booking sector has not gone unnoticed by traditional hospitality incumbents and established OTAs. Major hotel chains and travel conglomerates have responded by bolstering their own direct-booking loyalty programs, offering exclusive perks, mobile check-ins, and personalized experiences that third-party super apps cannot easily replicate.
Executives within the traditional OTA space have publicly downplayed the threat of everyday utility apps capturing complex travel bookings, arguing that booking a hotel or a multi-leg vacation requires specialized inventory management, comprehensive customer service support, and nuanced cancellation policies that differ vastly from hailing a cab or ordering takeout. Crafting a seamless customer support resolution when a hotel room is double-booked across time zones requires an operational infrastructure that is historically distinct from local logistics networks.
Nevertheless, industry analysts note that platforms like Uber and Airbnb are remarkably adept at outsourcing or building the necessary technological bridges to manage these complexities. By partnering with established bed-banks and travel software providers, Uber can plug into vast inventories of hotel rooms without needing to negotiate direct contracts with hundreds of thousands of independent properties worldwide.
Broader Impact on the Travel Landscape
The ultimate outcome of the competition between Uber’s frequency-driven model and Airbnb’s intent-driven model will likely reshape how consumers interact with travel services over the next decade.
If Uber successfully proves that daily transactional habits can dictate long-term travel purchasing behavior, it could permanently compress profit margins for traditional search-dependent OTAs. It would establish a precedent where consumers bypass dedicated travel portals entirely in favor of managing their entire digital lives—mobility, nourishment, local services, and global travel—within a single, unified application interface.
Conversely, if Airbnb successfully leverages its deep travel intent to expand its footprint into traditional hotel inventories and broader lifestyle categories, it will validate the thesis that consumers prefer specialized, highly curated ecosystems when making high-involvement purchasing decisions. In this scenario, the emotional resonance of planning a journey outweighs the convenience of an everyday utility app.
As both companies continue to iterate on their respective product roadmaps, the distinction between mobility platforms, delivery networks, and travel marketplaces is dissolving. The future of hospitality will not necessarily belong to the company with the most hotel rooms, but to the platform that most effectively captures consumer attention at the intersection of everyday habit and human aspiration.