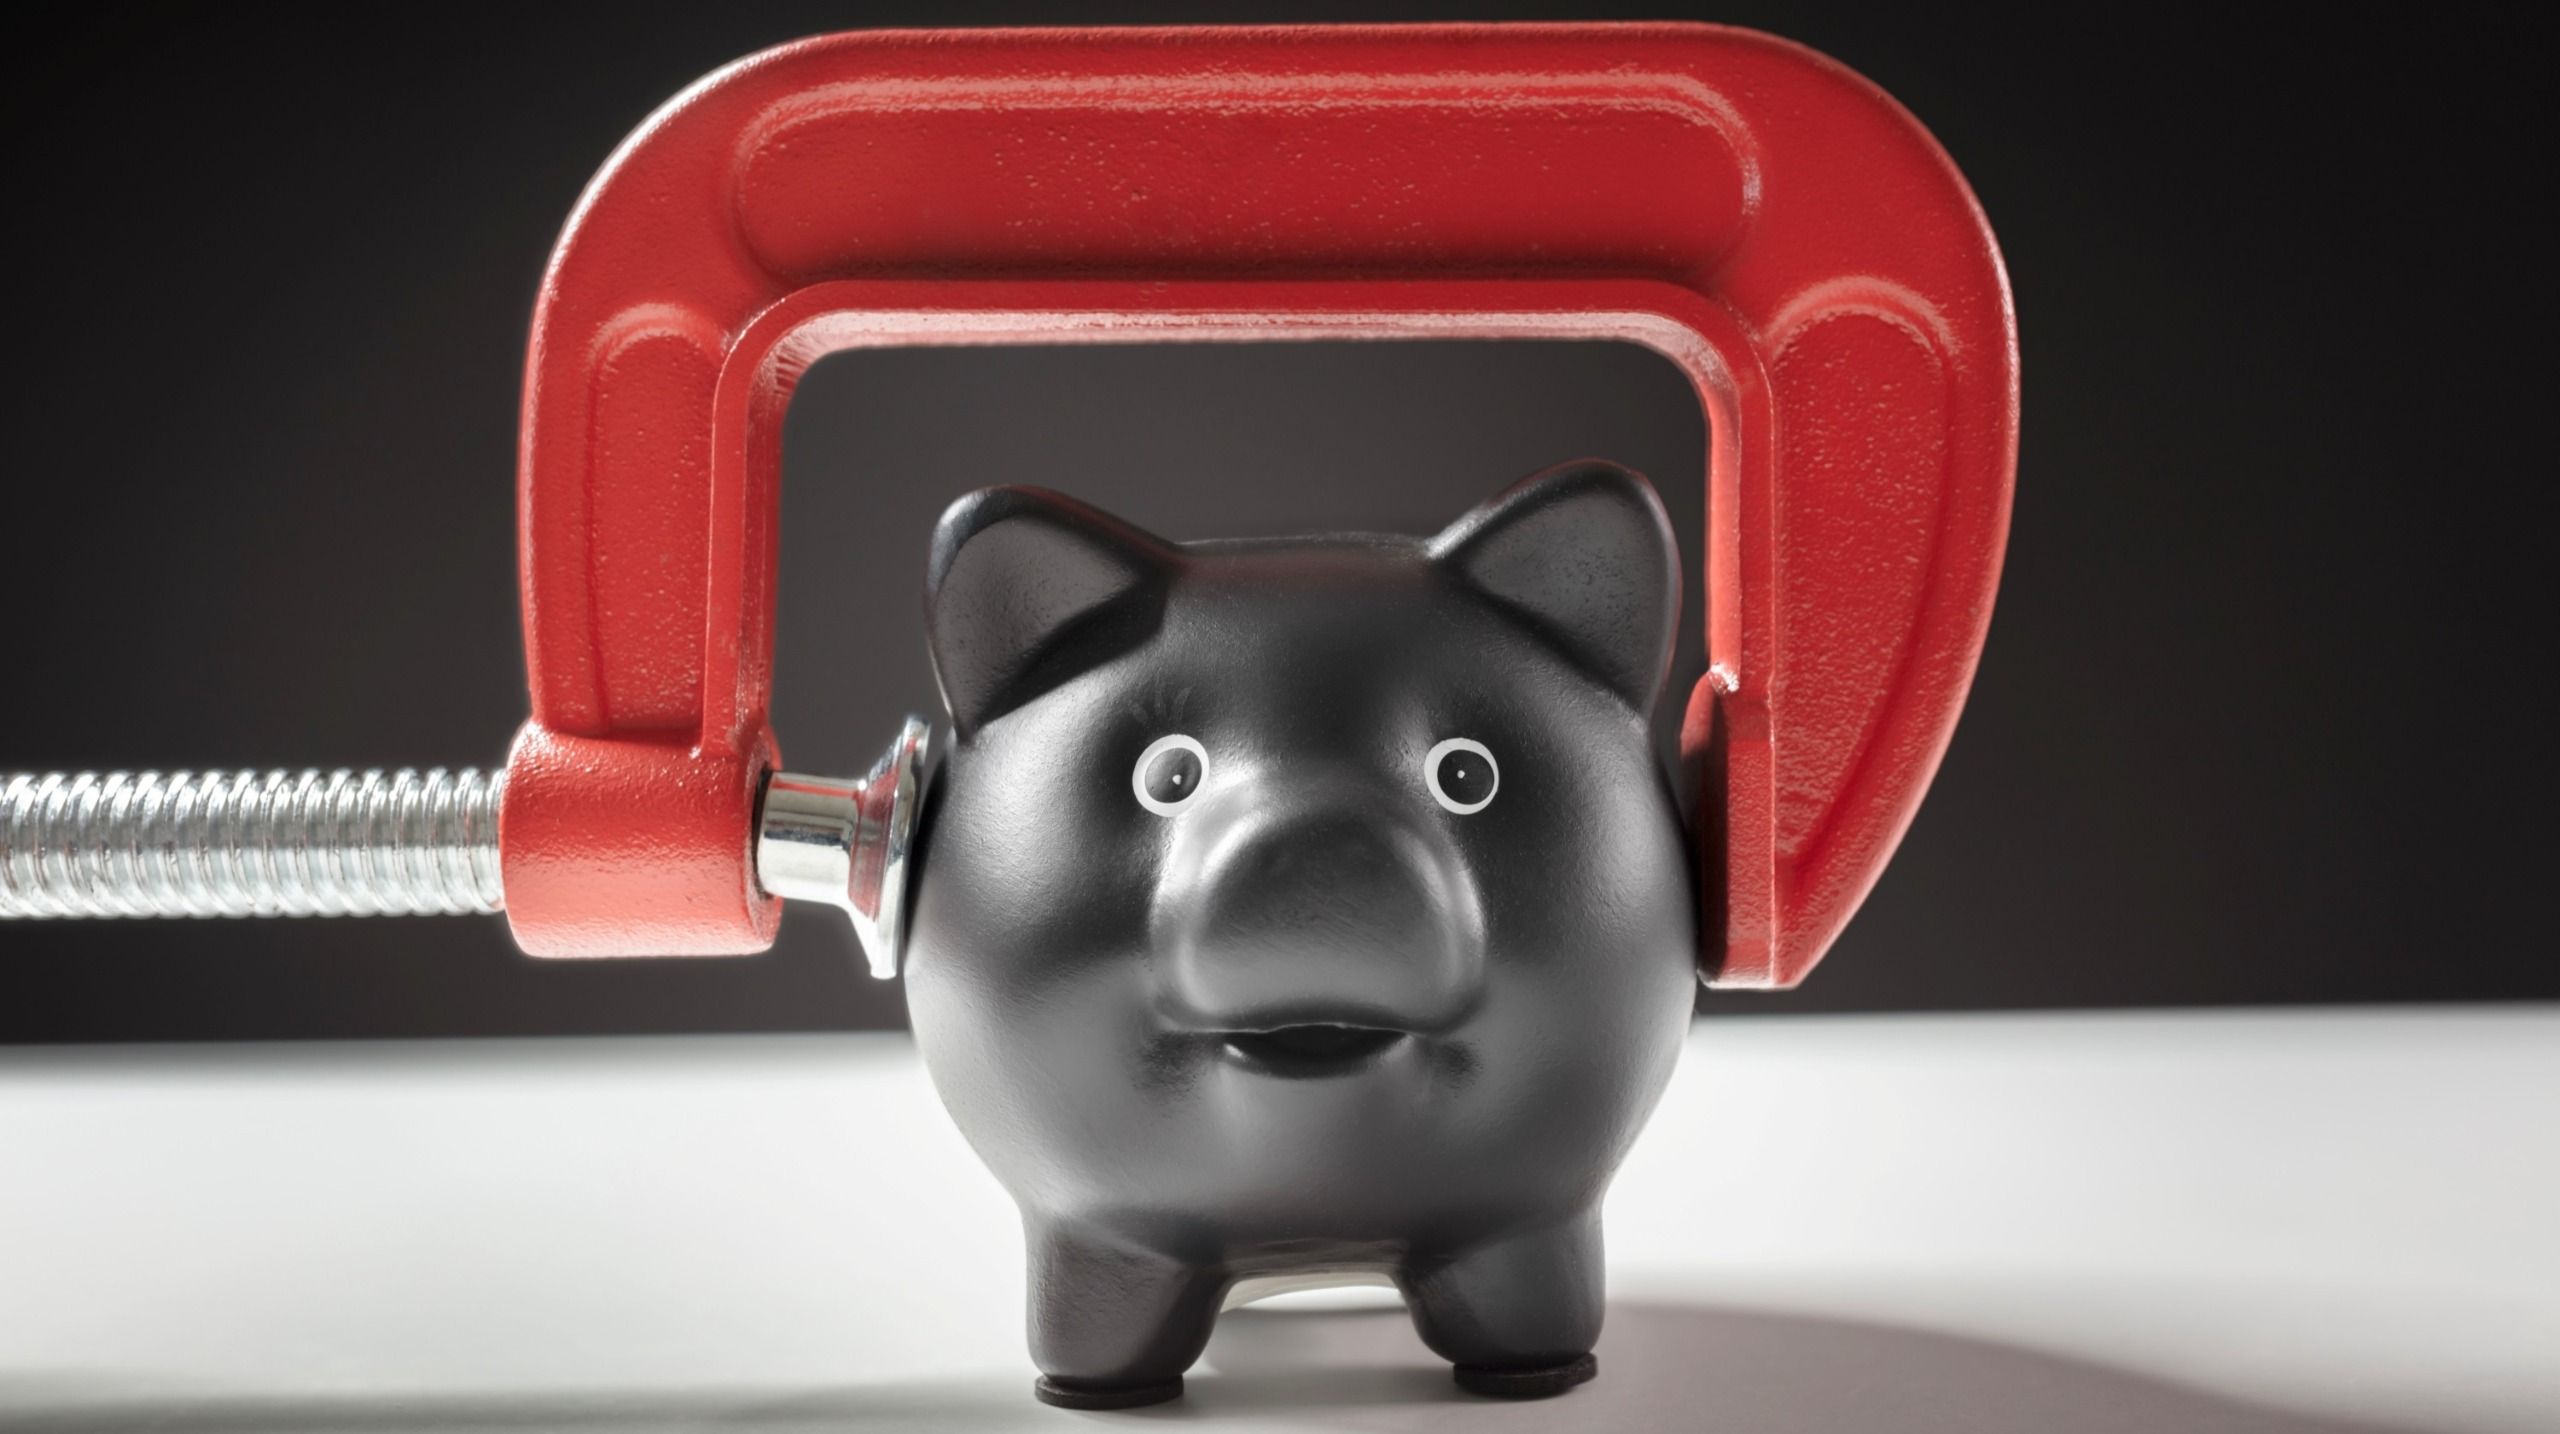
The current economic landscape presents a paradox for the average household: while employment figures remain relatively stable, the compounding effects of persistent inflation, elevated interest rates, and the exhaustion of pandemic-era savings have placed a vice-like grip on personal finances. As consumers navigate this environment, the traditional strategies for building wealth are being tested, forcing a re-evaluation of how individuals approach budgeting, debt management, and long-term financial planning.
The Macroeconomic Backdrop
The roots of the current financial squeeze can be traced back to the post-pandemic recovery period. Following the massive fiscal stimulus packages of 2020 and 2021, the global economy experienced a surge in demand that supply chains were ill-equipped to handle. This supply-demand imbalance, exacerbated by geopolitical instability and energy price volatility, triggered the highest inflation rates seen in four decades.
Central banks, led by the Federal Reserve in the United States, responded with a series of aggressive interest rate hikes. While these measures were intended to cool the economy and bring inflation back toward the 2% target, they also significantly increased the cost of borrowing. For the average consumer, this translated into higher mortgage rates, more expensive auto loans, and double-digit interest rates on credit card balances.
A Chronology of Financial Strain
The progression of this economic pressure can be categorized into three distinct phases over the past 36 months:
- The Inflationary Surge (2022): As consumer prices for essentials—particularly fuel, groceries, and housing—began to climb, households initially relied on the excess savings accumulated during the pandemic. Real wage growth turned negative for many workers, meaning that despite pay raises, purchasing power was effectively in decline.
- The Interest Rate Pivot (2023): As the Federal Reserve moved to tighten monetary policy, the cost of credit surged. This period marked a transition from a "spending-based" recovery to a "debt-management" crisis for many households. The focus shifted from discretionary consumption to covering the rising costs of servicing existing debt.
- The Credit Crunch and Delinquency Rise (2024–2025): Recent data from the Federal Reserve Bank of New York indicates that credit card delinquency rates have begun to rise, particularly among younger demographics and lower-income households. This signals that the "buffer" of savings has largely been depleted, leaving families vulnerable to unexpected financial shocks.
Supporting Data: The Erosion of the Safety Net
Financial data underscores the severity of this shift. According to recent Bureau of Economic Analysis (BEA) reports, the personal savings rate—the percentage of disposable income that people save—has consistently tracked below pre-pandemic levels. While the historic average typically hovered between 6% and 8%, recent quarters have seen this figure drop significantly, reflecting a population that is increasingly dipping into reserves to maintain their standard of living.
Furthermore, the average household debt burden has reached record nominal highs. While the ratio of debt-to-income remains below the peaks observed during the 2008 financial crisis, the cost of that debt has shifted. With credit card APRs frequently exceeding 20%, the velocity at which debt accumulates has increased, creating a "debt trap" for those unable to pay their balances in full each month.
Industry and Institutional Perspectives
Financial advisors and banking institutions have observed a marked change in client behavior. There is a documented decline in contributions to retirement accounts, such as 401(k) plans and IRAs, as workers prioritize immediate liquidity over long-term growth.
"We are seeing a trend where clients are choosing to pause their retirement contributions to clear out high-interest consumer debt," says a representative from a national financial planning consortium. "While this is a logical defensive maneuver in the short term, the opportunity cost of missing out on market compounding is a long-term risk that many are being forced to accept."
Consumer advocacy groups have also sounded the alarm regarding the predatory nature of "Buy Now, Pay Later" (BNPL) services. While these services offer short-term relief, their lack of standardized reporting means that many households are carrying significant hidden debt loads that do not appear on traditional credit reports until they have already reached a state of delinquency.
Analysis: The Implications for Wealth Building
The implications of this environment are twofold. First, the barrier to entry for wealth accumulation—such as homeownership or stock market investment—has become significantly steeper. When a household’s monthly budget is consumed by the interest on existing debt, the capacity for capital allocation into appreciating assets disappears.
Second, the psychological impact of this financial squeeze cannot be ignored. The "vice" gripping the piggy bank is not just a metaphor; it represents a tangible shift in consumer sentiment. When households feel financially insecure, they are less likely to participate in the broader economy through discretionary spending, which, ironically, can slow down economic growth and lead to the very recessionary conditions that policymakers are attempting to avoid.
Strategies for Financial Resilience
In this climate, financial experts emphasize three core pillars for maintaining stability:
- Prioritizing High-Interest Debt: Given the current interest rate environment, paying down credit card debt is effectively the highest "return on investment" a household can achieve. Even a 20% interest rate on a card acts as a guaranteed loss of wealth; eliminating that debt is mathematically equivalent to earning a 20% risk-free return.
- The "Emergency Fund" Rebuild: Financial planners suggest that the traditional three-to-six-month savings rule is now more critical than ever. In an era of economic volatility, having liquid cash is the only way to avoid relying on high-interest credit when an unexpected expense—such as a car repair or medical bill—arises.
- Reassessing Discretionary Outlays: Many households are utilizing "subscription audits" and lifestyle adjustments to reclaim margin. By identifying recurring, non-essential costs, families can redirect those funds toward debt reduction or emergency savings, thereby easing the pressure on their monthly cash flow.
The Road Ahead
The outlook for the remainder of the year remains contingent on central bank policy and labor market performance. Should inflation continue to moderate, there is a possibility that interest rates will be lowered, providing some relief to consumers carrying variable-rate debt. However, most economists caution that a return to the low-interest-rate environment of the 2010s is unlikely in the near term.
The financial "vice" currently affecting households is a symptom of a broader transition toward a more expensive, less subsidized economy. For the individual, the path forward requires a shift from passive saving to active management. As the era of "easy money" fades, the focus for the average household must remain on defensive financial hygiene: reducing expensive liabilities, prioritizing liquid assets, and maintaining a long-term view of wealth accumulation, even when the immediate economic environment demands sacrifices in the present.
Ultimately, the goal is to move from a state of reactive financial management to one of strategic planning. By understanding the macroeconomic forces at play and adjusting personal habits accordingly, individuals can better protect their financial health, ensuring that the "piggy bank" is not just protected from the vice, but is capable of growth despite the external pressure. The lessons learned during this period of economic contraction may well serve as the foundation for more resilient personal finance strategies in the decade to come.