Marriott International has reported a robust financial performance for the third quarter, driven by a surging global hotel network, soaring co-branded credit card revenues, and a broader-than-expected recovery across both luxury and limited-service properties. Gross fees climbed 14% to reach $1.52 billion during the quarter, contributing to a 17% increase in net income, which settled at $790 million. However, these strong results unfold against a backdrop of escalating tension between corporate leadership and hotel owners. A vocal faction of property owners has formally petitioned Marriott management for a larger share of loyalty program income—particularly targeting the lucrative streams generated by credit card partnerships—setting the stage for delicate negotiations as the hospitality giant continues to scale its operations globally.
The financial windfall is largely anchored by the remarkable expansion of Marriott’s credit card ecosystem and portfolio growth. During a recent earnings call, Chief Financial Officer Jen Mason highlighted the phenomenal trajectory of co-branded credit card fees, noting they are projected to surge in the high 30% range for the full fiscal year. This category has become a primary profit engine for modern hospitality companies, leveraging brand loyalty to generate steady streams of fee-based income independent of room nights.
Yet, this exact revenue stream has sparked friction. Earlier this year, a coalition of hotel owners addressed a joint letter to Marriott’s executive leadership. The correspondence argued that the current distribution model for loyalty income fails to reflect the rising operational costs borne by individual property owners. Because these credit card programs rely heavily on the everyday engagement and physical footprint of franchised and managed hotels, owners maintain they are entitled to a more substantial portion of the billions generated by these financial products.
Despite these underlying grievances, Marriott’s soaring financial metrics afford the corporation substantial leverage in ongoing and future discussions with its ownership network. Worldwide revenue per available room (RevPAR), a critical industry metric gauging both occupancy and average daily rates, jumped 6.5% year over year. This performance dramatically outperformed the company’s conservative projections issued in August, which estimated worldwide RevPAR growth between 3.5% and 4%. Furthermore, CFO Jen Mason pointed to a solid, enterprise-wide improvement in hotel operating margins, signaling that profitability gains are trickling down to the operational level rather than remaining confined to corporate headquarters.
A Chronological Look at Marriott’s 2026 Fiscal Trajectory
To understand how Marriott reached its current financial and operational standing, it is necessary to examine the events and macroeconomic shifts that have shaped the hospitality sector throughout the year.
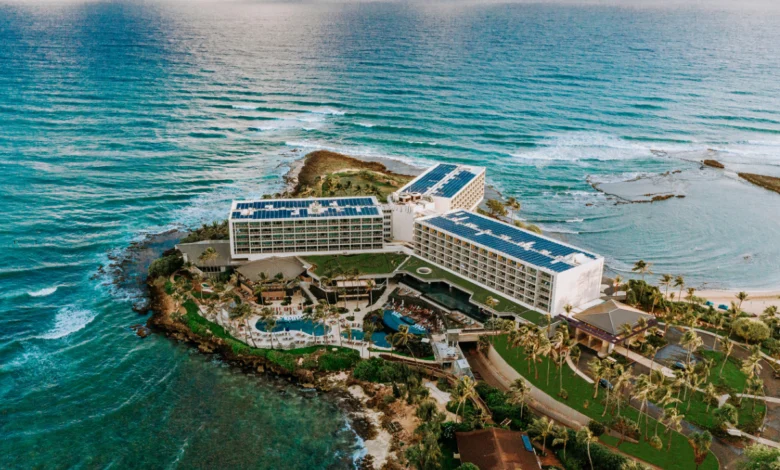
At the close of the first quarter, Marriott leadership struck an optimistic yet cautious tone as international travel continued its post-pandemic normalization. While luxury and resort destinations—such as The Ritz-Carlton Oahu Turtle Bay and similar flagship properties—demonstrated resilient demand, urban business travel and limited-service hotels experienced uneven recoveries.
By the time of the second-quarter earnings call in August, management had outlined a steady trajectory, forecasting modest global RevPAR growth of 3.5% to 4% for the remainder of the year. During this mid-year period, however, rumblings among hotel owners began to crystalize. Recognizing the exponential growth in co-branded credit card revenues, ownership groups began organizing to formalize their demands for a larger slice of the loyalty pie.
As the third quarter progressed into autumn, macroeconomic indicators shifted in favor of the hospitality industry. Consumer demand remained robust despite lingering inflationary pressures, and corporate travel budgets rebounded faster than anticipated. When the final tallies for the third quarter were compiled in late October and early November, they shattered the cautious forecasts made just months prior. Gross fees reaching $1.52 billion and net income hitting $790 million validated the aggressive expansion of Marriott’s branded network, even as property owners maintained pressure on executive management regarding fee-sharing structures.
Broadening Recovery Across the Portfolio
One of the most encouraging takeaways from Marriott’s third-quarter report is the breadth of the recovery across its vast portfolio of brands. Historically, luxury and upper-upscale properties lead recoveries because affluent travelers maintain discretionary spending power during economic transitions. However, the third quarter of this year demonstrated that the momentum has successfully penetrated every tier of the company’s lodging ecosystem.
Most notably, limited-service hotels—properties traditionally catering to budget-conscious business travelers and road-trippers—posted their third consecutive quarter of strong RevPAR gains, surging by more than 6% year over year. This sustained outperformance in the limited-service segment indicates that demand is broad-based, spanning extended-stay brands, select-service urban hotels, and suburban properties alike.
The strength in limited-service portfolios is particularly vital for Marriott’s development pipeline. Franchisees who invest in mid-tier and select-service models rely heavily on predictable cash flows and low operational overhead. The consecutive quarters of RevPAR growth provide these owners with much-needed financial breathing room, even as debates over loyalty income distribution continue to simmer in the background.
The Economics of Loyalty and Credit Card Partnerships
The modern hospitality business model has fundamentally transformed over the past decade. While hotels historically profited almost exclusively from selling overnight accommodations and food-and-beverage services, hotel chains like Marriott have increasingly evolved into loyalty-marketing organizations.
Programs such as Marriott Bonvoy serve as powerful moats, retaining millions of members through tiered benefits, point accumulations, and exclusive redemption opportunities. The crown jewel of this ecosystem is the co-branded credit card portfolio, operated in partnership with major financial institutions. These cards allow consumers to earn loyalty points on everyday purchases, generating billions of dollars in annual transaction fees and partnership revenue for the parent company.
Under standard franchising and management agreements, a portion of these loyalty revenues is funneled back into the system to fund marketing campaigns, reservation infrastructure, and member benefits. However, as credit card revenues have scaled exponentially—evidenced by the projected high-30% growth rate cited by CFO Jen Mason—hotel owners argue that the formula governing revenue distribution is outdated.
Owners point out that they bear the operational costs of honoring loyalty rewards, upgrading elite members, and maintaining brand standards on the ground. Consequently, they view the refusal to share a larger percentage of credit card proceeds as a misalignment of incentives. Conversely, corporate leadership maintains that centralizing these funds allows for massive global marketing campaigns and digital platform investments that ultimately drive higher booking volumes to every hotel in the network.
Fact-Based Analysis of Implications for the Industry
Marriott’s latest financial disclosure carries significant implications for the broader hospitality sector, influencing owner-operator dynamics, franchising trends, and competitive positioning against rival giants like Hilton and Hyatt.
First, the widening gap between corporate fee generation and owner profitability will likely accelerate discussions regarding contract terms across the entire hotel industry. If major hotel chains continue to post record fee revenues while individual property owners grapple with rising labor, insurance, and maintenance costs, ownership groups may become increasingly selective about which brands they choose to partner with for new developments. Collective bargaining and organized owner associations could become standard features of franchise negotiations, altering the traditional power dynamic between corporate franchisors and independent asset owners.
Second, the strong performance of limited-service hotels underscores the resilience of value-driven travel segments. As consumers become more discerning with their travel budgets, brands that offer reliable quality at accessible price points are capturing significant market share. This trend is expected to steer future development pipelines toward select-service and extended-stay models, which offer faster construction timelines and higher initial return on investment for developers.
Finally, Marriott’s financial strength provides it with a distinct competitive advantage in technology and digital infrastructure investments. With gross fees surpassing $1.52 billion in a single quarter, the company possesses the capital necessary to enhance its proprietary booking platforms, integrate artificial intelligence into customer service operations, and expand its footprint into emerging luxury and lifestyle segments.
As Marriott navigates the remainder of the fiscal year, executive leadership will need to balance the immense satisfaction of shareholders with the legitimate concerns of the hotel owners who form the physical backbone of its global network. How management resolves the push-and-pull over loyalty program revenue will likely set a crucial precedent for the future of hotel franchising and brand management worldwide.
Related posts: