The Psychological Price of the American Dream: How Housing Instability and the Shift to Renting Impact Well-Being

For generations, the acquisition of residential property has stood as the ultimate economic milestone in the United States—a tangible physical manifestation of the American dream and a universally recognized rite of passage into adulthood. Yet, the architectural landscape of this foundational concept has undergone a profound transformation over the past half-decade. Driven by an unprecedented convergence of economic pressures—including a persistent lack of housing inventory, stubbornly elevated mortgage interest rates, and an inflationary surge in construction and purchasing costs—the modern real estate market has locked out millions of prospective buyers.
Consequently, younger generations are renting at historical rates unseen in prior decades. Data from the National Association of Realtors highlights a striking shift in societal milestones: the median age of a first-time homebuyer in the United States reached 40 by 2026. This stark delay in property acquisition has forced researchers, sociologists, and economists to re-examine the traditional paradigm of housing tenure. Beyond the immediate financial calculations of equity and interest rates, contemporary scientific inquiry is now probing a much deeper question: How does this seismic shift from ownership to permanent renting alter our psychological well-being, our social fabric, and even our biological aging?
The Evolution of the Housing Crisis: A Five-Year Timeline
To understand the modern psychology of housing, one must examine the macroeconomic trajectory that reshaped the property market between 2020 and 2026.
- 2020–2021: The onset of the global pandemic triggered a mass migration toward suburban and regional markets, supercharged by historically low interest rates. Demand drastically outstripped supply, initiating a competitive frenzy that drove home prices up by double-digit percentages year-over-year.
- 2022–2023: In an effort to combat runaway inflation, the Federal Reserve embarked on an aggressive campaign of interest rate hikes. Mortgage rates more than doubled, transitioning rapidly from historic lows near 3% to peaks hovering above 7%. This monetary tightening created a "lock-in effect," where current homeowners holding low-rate mortgages refused to sell, freezing inventory levels.
- 2024–2025: Affordability metrics reached historic nadirs. The gap between the cost of servicing a median-priced mortgage versus paying median rent widened significantly. Institutional investors acquired single-family housing stock, converting potential starter homes into corporate rental properties and further entrenching the reliance on leasing.
- 2026: The median age of first-time buyers officially hits 40. Renting transitions from a temporary transitional phase for young adults into a long-term, multi-generational reality for significant segments of the population.
Are Homeowners Actually Happier? Dissecting the Data
The cultural narrative surrounding property ownership has long promised enduring happiness. However, empirical research reveals a picture that is considerably more nuanced.
When evaluating housing satisfaction—how an individual feels about the physical structure and immediate living environment—property owners consistently report higher contentment than renters. Furthermore, this satisfaction demonstrates remarkable longevity. A long-term longitudinal study conducted in Germany by economists Clark and Diaz-Serrano (2021) established that individuals who transition into owned homes experience an immediate spike in housing satisfaction that shows little to no fading even five consecutive years into occupancy.
However, cognitive appraisal of one’s housing does not automatically translate to overall life satisfaction. A separate German cohort study tracking participants over extended periods (Will & Renz, 2024) uncovered a critical disconnect: while acquiring a home successfully elevated housing satisfaction, it exerted no statistically significant lasting effect on overall life satisfaction.
The primary culprit behind this stagnation is financial strain. In these longitudinal analyses, the psychological burden of servicing a high-cost mortgage emerged as a major detractor from general well-being. The monthly financial obligation of a home loan frequently generates enough stress to neutralize the psychological advantages derived from property ownership itself.
This financial nuance is further illuminated by comprehensive multinational research utilizing data from the United States, the United Kingdom, and Australia (Clark et al., 2025). The study revealed that the so-called "owners are happier" gap is driven almost exclusively by individuals who own their homes outright—free of mortgage debt. Conversely, homeowners carrying substantial mortgages and minimal equity experienced a steep erosion of this psychological advantage, mirroring the stress levels of long-term renters.
The Psychological and Biological Toll of Renting
While the financial ledgers tell one story, the broader behavioral and biological metrics paint a compelling picture of how different housing tenures impact human health.
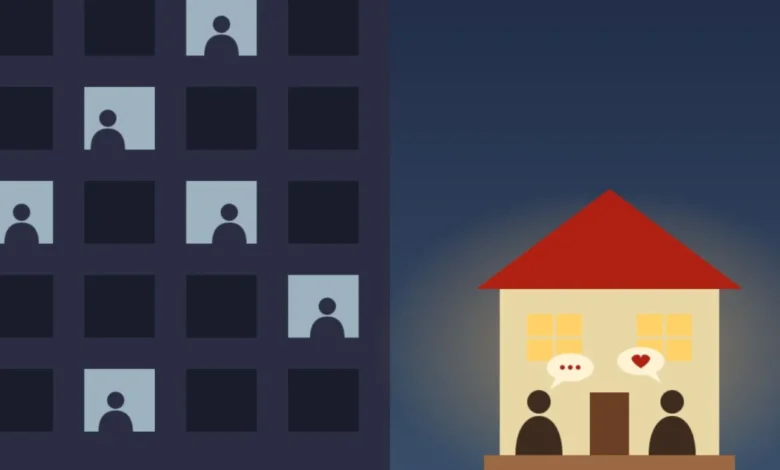
In a massive poll encompassing over 10,000 adults in the United Kingdom (Belonging Forum, 2024), stark disparities emerged regarding social connectedness. Approximately 40 percent of renters surveyed reported chronic feelings of loneliness, compared to just 29 percent of individuals who owned their homes outright. Additionally, renters exhibited significantly lower rates of neighborhood integration: only 43 percent reported knowing their neighbors well, contrasted with 69 percent of outright homeowners. Renters were also markedly less satisfied with the quality and depth of their friendships.
Critics of such observational polls frequently note confounding demographic variables—renters tend to be younger, earn lower median incomes, and experience higher residential mobility, all of which are independent risk factors for social isolation. Yet, the biological markers associated with renting suggest that the impacts extend far beyond temporary loneliness.
In a landmark biomarker study of approximately 1,400 UK adults (Clair, Baker, & Kumari, 2024), researchers examined patterns of DNA methylation—a recognized molecular marker of biological aging at the cellular level. The findings startled the scientific community: individuals living in private rental housing displayed biological aging profiles significantly older than their home-owning peers. To contextualize the effect size, the accelerated cellular aging associated with private renting was nearly twice the magnitude of the aging effect linked to unemployment versus employment, and fully 50 percent greater than the biological impact of being a current smoker versus a lifelong non-smoker.
While the observational nature of the study precludes a definitive causal declaration, subsequent systematic reviews help clarify the underlying mechanisms. A comprehensive meta-analysis of 22 studies evaluating renter populations (Talmatzky et al., 2026) pointed directly to structural instability as the primary vector of harm. Housing instability—operationalized as frequent, involuntary residential moves, the constant threat of eviction, and severe rent burdens—was directly linked to deteriorating mental health in 12 out of 14 studies that examined the metric. Similarly, disproportionately high rent-to-income ratios correlated negatively with psychological stability in six out of nine studies. The fundamental issue, researchers conclude, may not be the act of renting itself, but rather the structural insecurity and lack of autonomy that frequently accompany it.
Economic Implications and Asset Accumulation
Beyond the immediate psychological landscape, the modern difficulty of achieving homeownership carries profound long-term economic consequences. In financial terms, a mortgage operates structurally as a forced savings mechanism.
For many middle- and lower-income households, the disciplined monthly payment toward principal reduction serves as the primary engine for generational wealth creation. Money funneled into a mortgage transforms over decades into liquid or transferable equity, providing a robust financial buffer in retirement. Renters, conversely, miss out on this compounding asset accumulation, leaving them heavily reliant on external retirement vehicles and social safety nets.
This dynamic has reinforced class stratification among younger generations. Economists note that the widening wealth gap between those who acquired property prior to the 2022 interest rate hikes and those locked into the modern rental market will likely shape economic mobility for decades to come.
Bridging the Gap: Cultivating Stability Without a Deed
Given that macroeconomic realities will likely keep first-time homeownership out of reach for millions of citizens well into their late 30s and beyond, experts emphasize that the psychological benefits of homeownership are not entirely exclusive to property deeds.
Consumer behavior research into access-based consumption models—such as the psychological divergence between car-sharing and car ownership (Bardhi & Eckhardt, 2012)—suggests that human beings derive a sense of responsibility, identity construction, and psychological grounding from deep-seated physical investment in their surroundings. However, these benefits can be artificially replicated through behavioral intentionality.
Urban planners and community psychologists suggest that renters can mitigate many of the negative psychological impacts associated with housing insecurity by intentionally cultivating local roots. Strategies include:
- Prioritizing Lease Longevity: Selecting housing options that offer multi-year lease agreements to minimize the psychological stress of frequent relocation.
- Deliberate Community Integration: Actively participating in neighborhood associations, local civic groups, and social networks to combat the loneliness epidemic highlighted in national data.
- Physical Personalization: Within the constraints of rental agreements, investing personal effort into creating a stable, aesthetically comforting living space that fosters home-like psychological attachment.
The Broader Outlook
Ultimately, the cultural obsession with property ownership risks overshadowing the foundational pillars of human well-being. While the empirical data confirms that owning a home outright—or managing a sustainable mortgage—correlates with higher residential satisfaction and stronger community ties, it remains only one variable in a complex equation.
As economists, public health officials, and policymakers grapple with the structural realities of the housing market in the mid-2020s, the consensus among behavioral scientists is clear. Doing meaningful work, maintaining physical health, and nurturing robust, supportive social networks with friends and family remain vastly superior determinants of a flourishing life, superseding the societal pressure to achieve traditional homeownership at the expense of financial and mental stability.